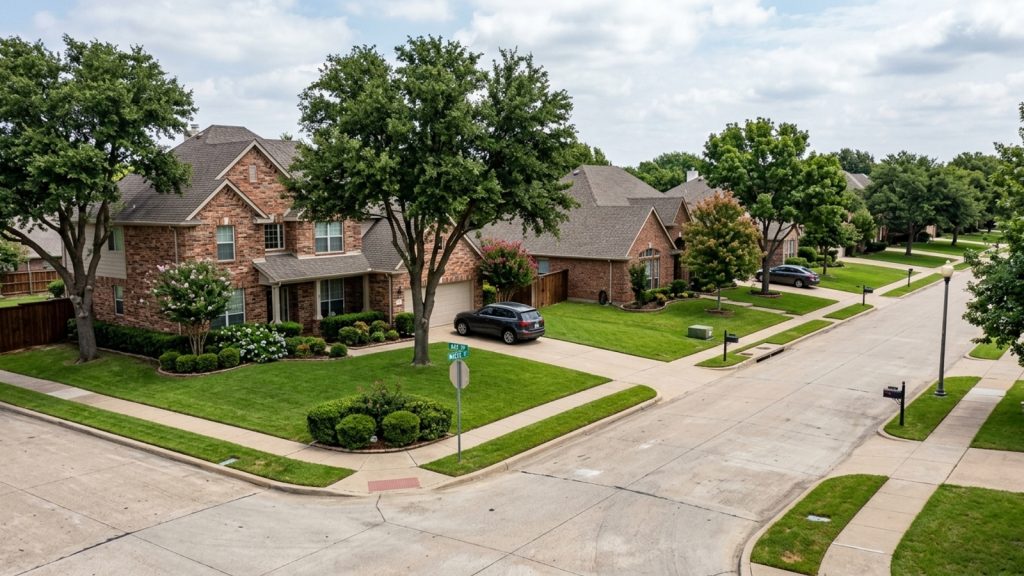
The median sale price in Plano, TX sits around $540,000 as of mid-2026. If you’re buying near that number, especially as first-time home buyers in Plano, TX, you need a real handle on what borrowing costs look like right now – not a rough idea, but actual figures you can plug into a monthly budget.
Homes here are going under contract in about 35 days from listing. That’s not a lot of time to scramble for financing. Buyers who already know their rate and their payment walk into offers with a confidence that buyers who are still shopping lenders simply don’t have.
Where Texas Interest Rates Stand Right Now
As of late August 2026, the average 30-year fixed mortgage rate across Texas falls between 6.6% and 6.99%. That range is real, and where you land inside it depends on your lender and your financial profile – not some arbitrary difference between one city and another.
The Federal Reserve doesn’t set mortgage rates directly, but their policy decisions move the bond market, and the bond market moves your rate. What that means practically is that rates shift daily based on national economic data. A rate you see on Monday morning may not be the rate you see Thursday afternoon.
That’s exactly why you should get quotes from multiple lenders. Local credit unions and national banks often price the same loan differently. On a $400,000 loan, half a percentage point is more than $100 a month. Comparing estimates side by side is the most straightforward way to find the lowest cost.
15-Year and 30-Year Fixed Averages
Most buyers choose a 30-year fixed-rate mortgage because it keeps the monthly payment lower. Current Texas averages for that product hover just below 7% – Forbes Advisor reported a 6.738% average APR for a 30-year loan this month.
A 15-year fixed loan typically carries a lower interest rate, and current Texas averages for that product run from roughly 5.9% to 6.17%. The tradeoff is a higher monthly payment. If you can absorb it, you’ll save tens of thousands of dollars in interest over the life of the loan.
Recent Trends in the Collin County Market
Plano currently has about 702 homes for sale – roughly 2.8 months of supply. Sellers are receiving an average of 97.9% of their list price, which tells you inventory is tight enough that there isn’t much room to negotiate on price.
Adjustable-rate mortgages offer lower initial rates than fixed products. Those rates stay locked for an introductory period of five to ten years before adjusting annually. Whether an ARM makes sense depends almost entirely on how long you plan to stay in the home.
What Determines Your Personal Interest Rate
Lenders are really looking at three things: your credit history, your down payment, and the type of property you’re buying. Together, those factors tell underwriters how much risk they’re taking on.
The advertised averages are just a starting point. Your actual quote will be shaped by your specific application. That’s not a warning – it’s just how the process works, and knowing it lets you do something about it before you apply.
Paying down existing debts before you submit an application lowers your debt-to-income ratio, which lenders view favorably. Small moves on your financial profile can translate into a meaningfully better rate.
Credit Score Thresholds
Conventional lenders typically reserve their lowest rates for borrowers with credit scores of 740 or higher. Drop into the 600s and you’ll likely see a higher quote. It’s a direct relationship – a better score produces a lower monthly payment.
Down Payments and Loan-to-Value
Your loan-to-value ratio compares what you’re borrowing to what the home costs. Put 20% down on a $540,000 Plano home and your LTV drops to 80%. Lenders offer better rates at lower LTV ratios because you have more equity at stake from day one.
Property Types
Single-family detached homes generally secure the most favorable rates. Condominiums and townhomes tend to carry slightly higher rates – lenders view attached properties as marginally riskier, and that view shows up in the pricing.
Home Loan Options in Collin County
The 2026 conforming loan limit for Collin County is $832,750 for a single-family home. Because no Texas county qualifies as a high-cost area, that limit applies statewide.
You have several loan types to choose from, and the right one depends on your down payment funds and your military service history. Government-backed loans operate under different rules than private mortgages – different rate structures, different mortgage insurance requirements.
Conventional Mortgages
Fannie Mae and Freddie Mac set the guidelines for conventional loans. You can get one with as little as 3% down, though anything under 20% requires private mortgage insurance. For Plano buyers with strong credit, these are the most common choice.
FHA Mortgages
FHA loans are backed by the Federal Housing Administration and carry a separate 2026 limit of $563,500 in Collin County. They allow down payments as low as 3.5% and are more forgiving of lower credit scores. You’ll pay an upfront mortgage insurance premium plus annual premiums.
VA Mortgages
If you’re a veteran or active-duty military, a VA loan lets you buy with zero down payment. These loans don’t require private mortgage insurance and typically offer lower rates than conventional products. You’ll need a Certificate of Eligibility to qualify.
Jumbo Financing
Borrow more than the $832,750 conforming limit and you’re in jumbo territory. Jumbo loans come with stricter credit requirements and typically larger down payments. Rates on jumbo products can sometimes run lower than conventional rates, depending on what a given lender is trying to do with their portfolio.
Texas First-Time Homebuyer Programs
Texas operates multiple housing finance agencies designed to help residents get into homes. They offer down payment assistance and favorable interest rates to buyers who qualify.
Eligibility depends on your household income and the purchase price of the property. Lenders who originate these loans must be approved by the specific agency – not every lender participates.
A state program can meaningfully reduce what you bring to closing. It’s worth asking your loan officer to run the numbers on both a standard mortgage and a state-assisted loan before you decide.
TDHCA Programs
The Texas Department of Housing and Community Affairs manages “The Texas Homebuyer Program.” Their “My First Texas Home” option is aimed at first-time buyers and veterans. “My Choice Texas Home” is open to repeat buyers as well.
TSAHC Options
The Texas State Affordable Housing Corporation is a nonprofit that offers its own loan products. “Homes for Texas Heroes” targets teachers, police officers, and other public servants. The “Home Sweet Texas Home Loan Program” serves low-to-moderate-income buyers across the state.
Both TSAHC programs can include Mortgage Credit Certificates and down payment grants. A Mortgage Credit Certificate gives you a dollar-for-dollar tax credit on a portion of the mortgage interest you pay each year – that’s real money back at tax time, not a deduction.
Frequently Asked Questions
Are mortgage rates in Plano typically higher or lower than the rest of the Dallas-Fort Worth area?
No, mortgage rates in Plano are generally the same as the rest of the Dallas-Fort Worth area. Rates are set by broader state averages – currently 6.6% to 6.99% for a 30-year fixed loan – not by city or zip code. Your personal financial profile matters far more than your address.
How do Plano’s property tax rates impact how much house I can afford at today’s interest rates?
Property taxes get factored into your debt-to-income ratio when a lender calculates your maximum loan amount. Texas relies on property taxes rather than a state income tax, so those annual bills can be substantial. The higher the tax bill, the less room you have in your monthly budget for principal and interest.
At what point during the Plano homebuying process should I lock in my mortgage rate?
Lock in your rate once your offer is accepted and you have a signed purchase contract. Most lenders offer a rate lock for 30 to 60 days, which covers the typical 35-day timeline it takes to close a home in Plano.
What credit score do local lenders require to qualify for the best conventional mortgage rates in Plano?
A score of 740 or higher is generally what lenders want to see before they’ll offer their lowest conventional rates. Borrowers with lower scores can still qualify, but they’ll likely face a higher Annual Percentage Rate (APR).
What happens if interest rates drop before my closing date on a Plano property?
It depends on your rate lock agreement. If you have a float-down option built in, your lender will lower your rate to match the market before closing. Without that feature, you’re locked to the rate you originally secured.
Are there any first-time homebuyer programs in Plano or Collin County that offer below-market interest rates?
Yes. Programs through the TDHCA and TSAHC offer competitive interest rates and down payment assistance. Both are available in Collin County for buyers who meet the income and purchase price limits.