What Should Buyers Know About Homeowners Insurance in Star Trail?
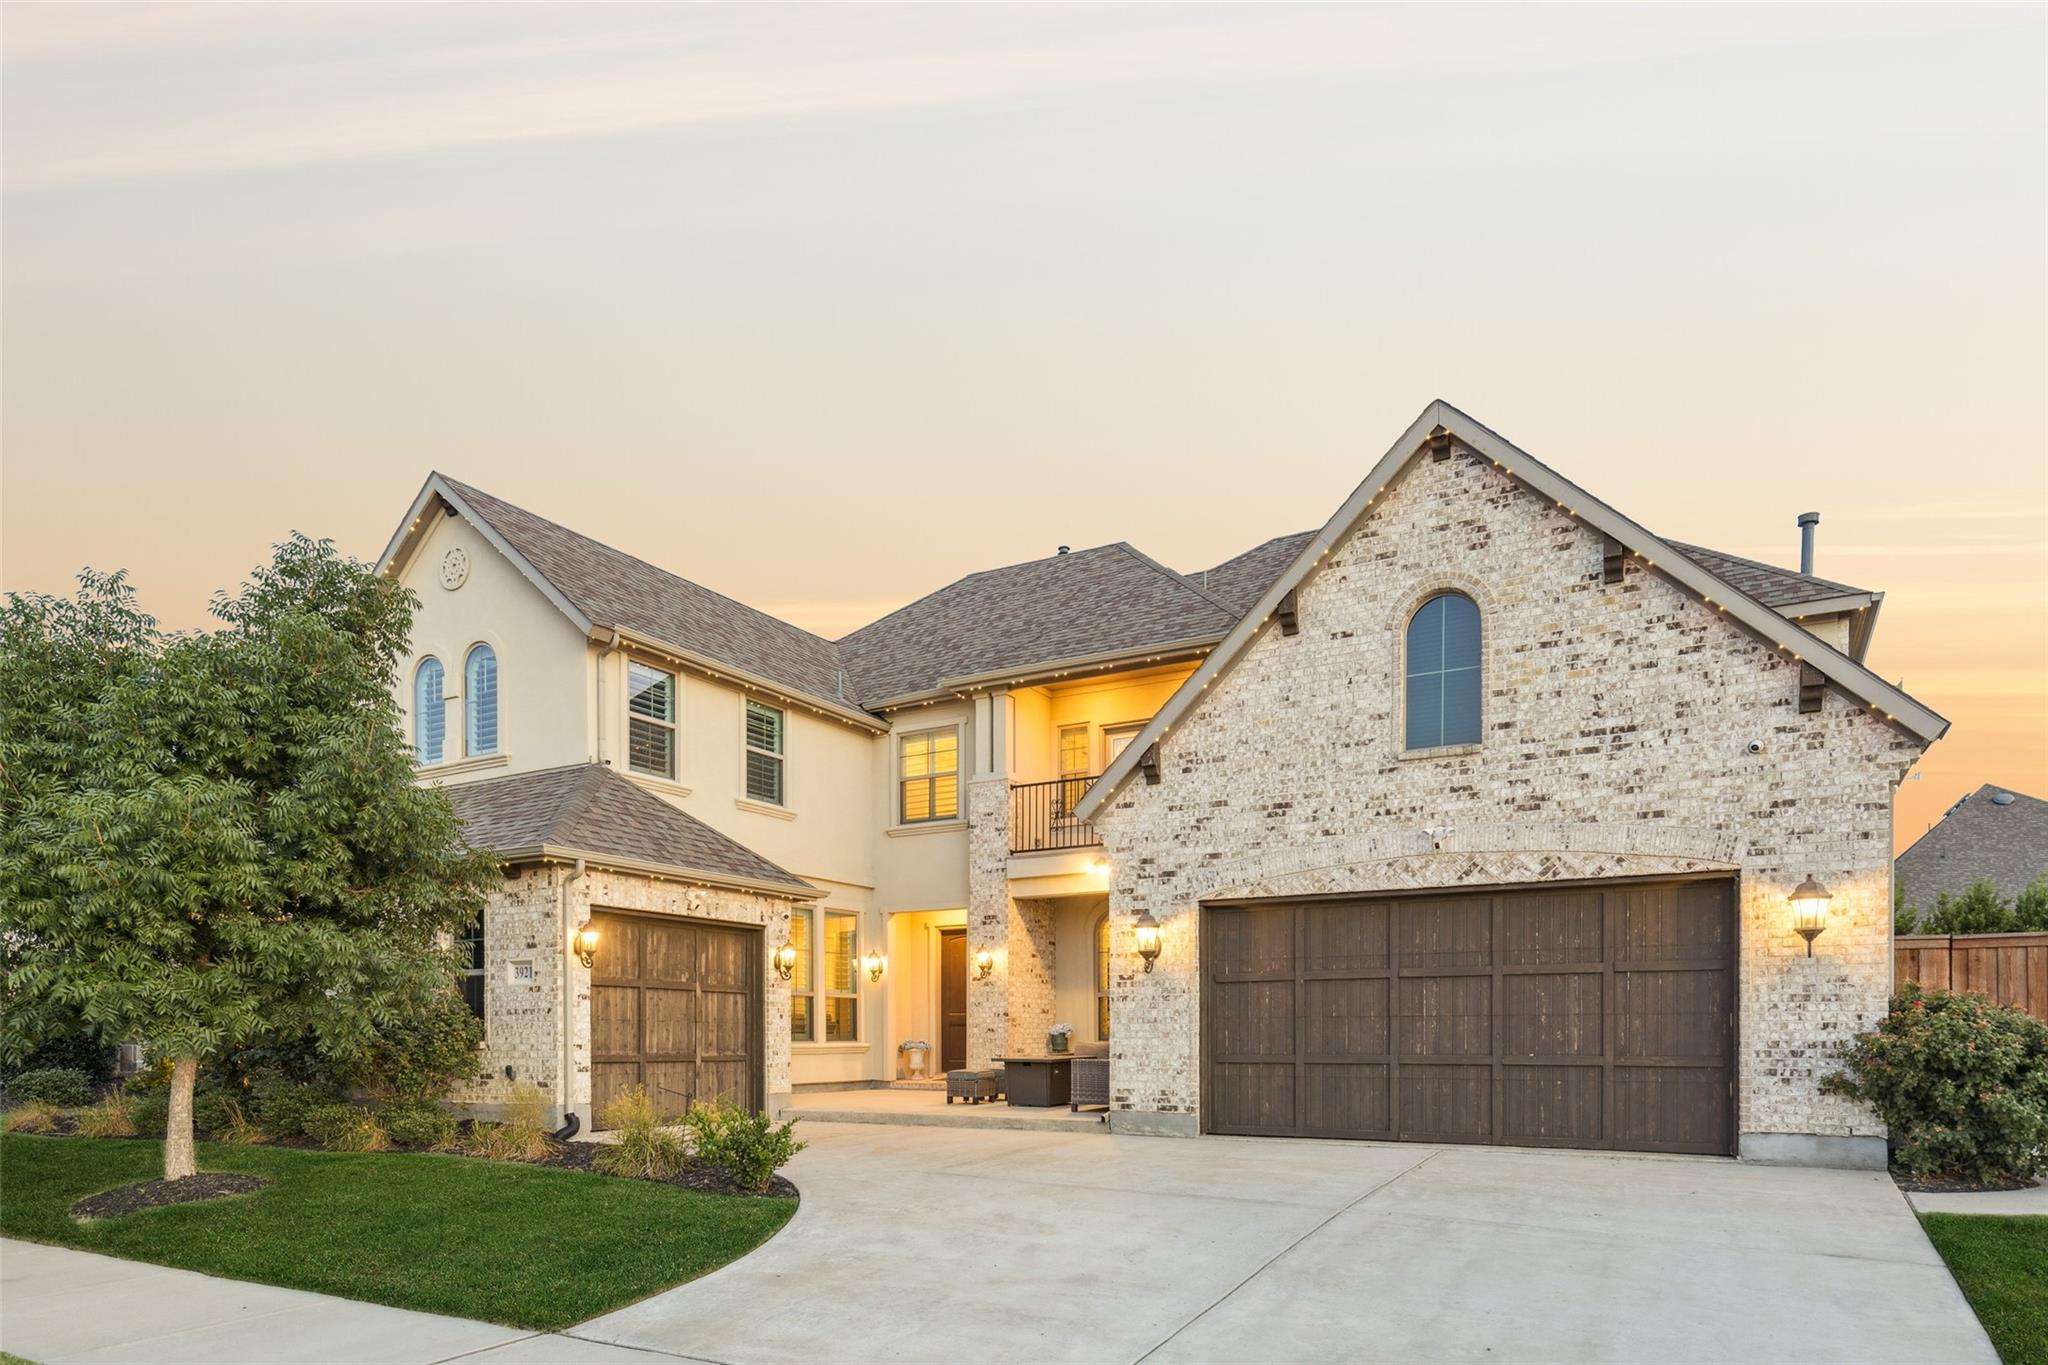
Star Trail buyers should obtain homeowners-insurance quotes early enough to evaluate coverage, deductibles and the true monthly housing cost before contractual deadlines.
Insurance pricing can vary based on the individual home, roof, construction details, replacement cost, selected coverage, deductibles, claims history and carrier. A prior owner’s premium or a broad Prosper estimate should not be treated as the cost for a specific buyer.
Current Star Trail Homes for Sale



What Buyers Should Evaluate
- Estimated dwelling replacement cost.
- Wind and hail deductibles.
- Roof age, material and condition.
- Water-damage and foundation coverage.
- Personal-property and liability limits.
- Pool, outdoor kitchen and other improvements.
- Available discounts and policy exclusions.
- The effect of the premium on monthly escrow and qualification.
Buyers should compare the policy terms—not just the premium. A lower quote may carry higher deductibles, narrower coverage or exclusions that materially increase the buyer’s risk.
When to Request Insurance Quotes
Waiting until immediately before closing can create unnecessary pressure. Buyers should begin the insurance conversation once a serious property is identified and update the quote if inspection findings reveal roof, electrical, plumbing or other conditions that could affect underwriting.
Insurance and New Construction
A newly built home may qualify for certain carrier discounts, but buyers should still confirm the replacement-cost estimate, deductibles and coverage for upgrades, outdoor improvements and personal property. The builder warranty and homeowners insurance serve different purposes and should not be treated as substitutes.
Why Independent Buyer Representation Matters With a Builder
The builder’s sales representative represents the builder’s interests. Their responsibility is to sell the builder’s homes and protect the builder’s position in the transaction—not to independently advise the buyer.
Having your own Realtor gives you someone focused on evaluating the transaction from your perspective, including:
- Builder contracts and deadlines.
- Lot selection and premiums.
- Floor plans and elevations.
- Structural options.
- Design-center pricing.
- Construction timelines.
- Inspection opportunities.
- Builder warranties.
- Financing incentives.
- Closing-cost assistance.
- Comparable resale homes.
- Competing builder inventory.
Builder Incentives and Negotiation Matter
One of the biggest advantages of experienced buyer representation is understanding what builders may be offering beyond the advertised base price.
An experienced Realtor who regularly works with builders may be aware of incentives, inventory pressures and negotiation opportunities that a buyer walking directly into the builder’s sales office may not know to ask about.
Those opportunities may include:
- Additional closing-cost assistance.
- Interest-rate buy-downs.
- Preferred-lender incentives.
- Design-center or upgrade credits.
- Lot-premium adjustments.
- Appliance or window-treatment packages.
- Inventory-home incentives.
- Price adjustments on completed or nearly completed homes.
Not every builder will negotiate every term, but buyers should understand what may be available before signing a contract.
The earlier a buyer establishes independent representation, the easier it is to evaluate the builder, compare incentives, review competing options and negotiate from a more informed position.
The builder has someone protecting its interests. A buyer should have someone focused on protecting theirs.
How Bale Real Estate Group Assists Star Trail Buyers
Gary and Linda Bale help buyers compare the specific property with Star Trail resale and builder inventory, coordinate due diligence, track contract deadlines, evaluate inspection findings and keep insurance, lending, appraisal, title and closing requirements moving together.
They do not select coverage or replace the advice of a licensed insurance professional. Their role is to help buyers recognize when insurance information affects the real estate decision and address it before a deadline becomes a problem.
Questions to Ask an Insurance Professional
- What replacement-cost estimate supports the dwelling limit?
- What are the wind, hail and all-other-peril deductibles?
- Are roof losses settled at replacement cost or actual cash value?
- Are water backup, foundation or service-line endorsements available?
- How are a pool and outdoor improvements covered?
- Which exclusions or underwriting conditions should the buyer understand?
A Prosper New-Construction Buyer’s Experience
“Linda was an outstanding advocate for our Highland Homes new construction purchase in Prosper. We were relocating and needed someone who actually understood North Dallas builders, taxes, and floor plans, not just open houses.
She planned tours around no PID/MUD communities and our must haves, helped us compare Highland and Tradition quotes with comps and options pricing, and stayed sharp when we changed elevation and contract details. When our pre-foundation inspection turned up with some issues, she went straight to the builder and kept pressure on so we weren’t left negotiating alone. She stayed with us from first tours through closing.
If you’re buying new construction in Prosper or the North Dallas area, especially from out of town, get your own Realtor and get Linda.”
“Buying a home is a major decision, and Linda Bale helped us feel confident throughout the entire process.”
“Their expert knowledge, attention to detail and commitment placed our home-buying experience on another level.”
Why Buyers Choose Bale Real Estate Group · Meet the Team · Proven Results · Client Testimonials
Watch: Determining What Home You Can Afford · Watch: Purchasing a New-Construction Home
Frequently Asked Questions
Does the seller’s current premium predict mine?
No. Coverage choices, deductibles, underwriting and buyer-specific factors can produce a different result.
Does a builder warranty replace homeowners insurance?
No. A warranty addresses specified construction obligations; insurance addresses covered losses under the policy.
Can insurance affect closing?
Yes. A lender generally requires acceptable coverage, and the premium may affect escrow and the total monthly payment.
Buying in Star Trail?
Let Bale Real Estate Group help you evaluate the property, builder or resale competition and due-diligence timeline.
Contact Bale Real Estate Group
Call or text 972-469-0332 · info@balerealestategroup.com
Clarity First. Pressure Never.