Top 1% Frisco & Plano Realtors | Bale Real Estate GroupTop 1% Frisco & Plano Realtors | Bale Real Estate Group

Top 1% North Texas Realtors with $65M+ in residential real estate volume, 110+ successful transactions and 80+ five-star reviews. Frisco, Plano, Prosper, Allen, McKinney & North Dallas.

  • Home
  • Search
  • Communities We Serve
    • University Park
    • Highland Park
    • Allen
    • Aubrey
    • Celina
    • Coppell
    • Dallas
      • Oakdale
    • Frisco
      • Chapel Creek
      • Country Club Ridge at The Trails
      • Custer Creek Farms
      • Edgestone at Legacy
      • Griffin Parc
      • Heather Ridge Estates
      • Newman Village
      • Park Place Estates
      • Phillips Creek Ranch
      • Richwoods
      • Shaddock Creek Estates
      • Starwood
      • Stonebriar
      • The Canals at Grand Park
      • The Fairways
      • The Hills of Kingswood
      • Villages of Stonebriar Park
    • McKinney
    • Plano
      • Avignon Windhaven
      • Cliffs of Gleneagles
      • Crystal Creek
      • Deerfield
      • Kings Gate
      • Lakeside on Preston
      • Normandy Estates
      • Shoal Creek
      • Wentworth Estates
      • Willow Bend Polo Estates
      • Willow Bend
      • Windrose Tower
    • Preston Hollow
    • Princeton
    • Prosper
    • Southlake
  • Buyers
    • Search Homes
    • Explore Communities
    • Buyer Resources
    • Relocating to North Texas
    • New Construction
    • Meet Gary & Linda
    • Contact Linda
  • Sellers
    • Thinking About Selling?
    • Pre-Listing Appointment
    • Seller Resources
    • Home Value & Pricing Strategy
    • Preparing Your Home for Sale
    • Proven Results
    • Contact Linda
  • Our Advantage
    • Why Sellers Hire Bale Real Estate Group
    • Why Buyers Choose Bale Real Estate Group
    • Meet the Team
    • Real Producers: Cover Story
    • Our Story
    • Client Testimonials
    • Proven Results
  • Videos
  • Contact

What Star Trail Sellers Should Know About Buyer Financing

Star Trail sellers should evaluate a buyer’s financing as part of the quality of the offer—not just the purchase price. Two offers with the same price can carry very different levels of risk depending on the buyer’s lender, loan approval, down payment, appraisal exposure, available cash and financing deadlines.

That matters because an accepted contract is only the beginning. A financed buyer still has to move successfully through underwriting, appraisal, lender conditions and closing.

Bale Real Estate Group helps Star Trail homeowners compare the complete strength of an offer so price, financing, timing and seller protection can be considered together.

Learn About Offer Strategy and Seller Protection

Current Star Trail Homes for Sale

950 Gentle Knoll Lane Prosper TX 75078
New Listing – 3 days on site
1 / 40
$600,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
3
BEDS
3
TOTAL BATHS
2,305
SQFT
950 Gentle Knoll Lane
Prosper, TX 75078
Star Trail Subdivision
2731 Douglas Lane Prosper TX 75078
New Listing – 4 days on site
1 / 4
$1,096,220
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,354
SQFT
2731 Douglas Lane
Prosper, TX 75078
Star Trail Subdivision
2750 Amber Lane Prosper TX 75078
New Listing – 4 days on site
1 / 5
$1,075,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
7
TOTAL BATHS
4,153
SQFT
2750 Amber Lane
Prosper, TX 75078
Star Trail Subdivision
2701 Savannah Ridge Prosper TX 75078
New Listing – 4 days on site
1 / 6
$990,530
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
3,847
SQFT
2701 Savannah Ridge
Prosper, TX 75078
Star Trail Subdivision
120 Miramar Drive Prosper TX 75078
New Listing – 5 days on site
1 / 40
$1,100,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
4
TOTAL BATHS
3,419
SQFT
120 Miramar Drive
Prosper, TX 75078
Star Trail Ph Nine Subdivision
2001 Harvard Avenue Prosper TX 75078
New Listing – 6 days on site
1 / 40
$1,595,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
4,750
SQFT
2001 Harvard Avenue
Prosper, TX 75078
Star Trail Ph One B Subdivision
2560 Miles Street Prosper TX 75078
New Listing – a week on site
1 / 11
$1,376,900
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,340
SQFT
2560 Miles Street
Prosper, TX 75078
Star Trail Subdivision
451 Margot Drive Prosper TX 75078
New Listing – a week on site
1 / 6
$1,249,900
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,664
SQFT
451 Margot Drive
Prosper, TX 75078
Star Trail Subdivision
2691 Douglas Lane Prosper TX 75078
New Listing – 2 weeks on site
1 / 26
$1,099,120
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,231
SQFT
2691 Douglas Lane
Prosper, TX 75078
Star Trail Subdivision
2420 Forestbrook Drive Prosper TX 75078
New Listing – 2 weeks on site
1 / 40
$968,850
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,790
SQFT
2420 Forestbrook Drive
Prosper, TX 75078
Star Trail Ph 10 Subdivision
1581 Turnberry Drive Prosper TX 75078
New Listing – 2 weeks on site
1 / 39
$1,280,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,169
SQFT
1581 Turnberry Drive
Prosper, TX 75078
Star Trail Ph Four Subdivision
841 Ivy Glen Court Prosper TX 75078
New Listing – 2 weeks on site
1 / 33
$1,039,999
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,593
SQFT
841 Ivy Glen Court
Prosper, TX 75078
Star Trail Ph One B Subdivision
1720 Lexington Avenue Prosper TX 75078
New Listing – 3 weeks on site
1 / 40
$1,099,999
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,633
SQFT
1720 Lexington Avenue
Prosper, TX 75078
Star Trail Ph One B Subdivision
2180 Shady Hill Drive Prosper TX 75078
New Listing – 4 weeks on site
1 / 37
$1,599,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
6
BEDS
7
TOTAL BATHS
4,551
SQFT
2180 Shady Hill Drive
Prosper, TX 75078
Star Trail Ph Eight Subdivision
2440 Dena Drive Prosper TX 75078
New Listing – 4 weeks on site
1 / 8
$1,179,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,204
SQFT
2440 Dena Drive
Prosper, TX 75078
STAR TRAIL PHASE TWELVE Subdivision
1990 Cornell Drive Prosper TX 75078
1 / 38
$1,275,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
5
TOTAL BATHS
3,876
SQFT
1990 Cornell Drive
Prosper, TX 75078
Star Trail Ph Five Subdivision
151 Cloverfield Trail Prosper TX 75078
Short Sale
1 / 2
$1,299,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,718
SQFT
151 Cloverfield Trail
Prosper, TX 75078
Star Trail Ph Nine Subdivision
2770 Douglas Lane Prosper TX 75078
1 / 4
$1,131,575
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,134
SQFT
2770 Douglas Lane
Prosper, TX 75078
Star Trail Subdivision
2720 Ambergate Lane Prosper TX 75078
Price Change – 4 weeks ago
1 / 5
$975,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
3,847
SQFT
2720 Ambergate Lane
Prosper, TX 75078
Star Trail Subdivision
2620 Acie Lane Prosper TX 75078
1 / 5
$950,380
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
5
TOTAL BATHS
3,461
SQFT
2620 Acie Lane
Prosper, TX 75078
Star Trail Subdivision

Current Star Trail inventory affects buyer leverage and the types of offers sellers may receive.

When buyers have more choices, sellers may see:

  • More financing contingencies.
  • Requests for seller concessions.
  • Longer closing timelines.
  • Greater sensitivity to appraisal and condition.
  • More negotiation over repairs or credits.

Understanding the buyer’s financing helps a seller evaluate how likely the contract is to reach closing—not simply how attractive the first page of the offer appears.

A Higher Offer Is Not Automatically the Stronger Offer

Consider two hypothetical offers.

One buyer offers a slightly higher price but has limited cash, a weak preapproval and significant financing conditions.

Another buyer offers a little less but has:

  • A strong lender.
  • Substantial funds available for closing.
  • A meaningful down payment.
  • A clear financing timeline.
  • Fewer potential obstacles between contract and closing.

The higher-priced offer may still be the best choice, but the seller should understand the additional risk before deciding.

The strongest offer is the one that best balances price, terms and probability of closing.

Start by Understanding the Buyer’s Preapproval

A financing letter is useful, but sellers should not assume every preapproval represents the same level of review.

Questions worth understanding may include:

  • Has the lender reviewed the buyer’s income?
  • Have assets been reviewed?
  • Has credit been evaluated?
  • Has the buyer already provided documentation?
  • Is the approval preliminary or has underwriting already reviewed the file?
  • Are there significant conditions remaining?

A stronger lender review can provide greater confidence than a quick qualification based largely on information supplied by the buyer.

The Quality of the Lender Matters

The lender becomes an important part of the transaction once a financed offer is accepted.

Sellers should consider whether the lender appears:

  • Responsive.
  • Experienced.
  • Familiar with the type and price range of the property.
  • Realistic about the proposed closing timeline.
  • Prepared to communicate throughout the transaction.

Problems with financing are not always caused by the buyer. Delays can also arise from incomplete documentation, underwriting issues, appraisal timing or poor lender communication.

A credible lender and realistic financing timeline can make an otherwise similar offer more attractive.

Understand the Buyer’s Down Payment

The size of the down payment can provide useful information, although it should never be evaluated in isolation.

A buyer making a larger down payment may have more flexibility if:

  • The appraisal comes in below the contract price.
  • Closing costs are higher than expected.
  • The lender requires additional reserves.
  • Another financial issue appears during underwriting.

A smaller down payment does not mean the buyer is unqualified. It does mean the seller should understand how much flexibility exists if circumstances change before closing.

Proof of Funds Helps Verify Cash Needed for Closing

A financed buyer may need cash for more than the down payment.

Depending on the transaction, funds may also be needed for:

  • Closing costs.
  • Prepaid expenses.
  • Reserves required by the lender.
  • Appraisal-gap obligations.
  • Repairs or improvements planned after closing.

Verifying that the buyer has the funds required for the proposed transaction can strengthen confidence in the offer.

Some Star Trail Buyers May Use Jumbo Financing

Because Star Trail includes substantial homes at higher price points, some buyers may use financing that requires a larger loan and additional lender review.

Loan limits and lender requirements change, so sellers should not rely on a static dollar threshold when evaluating an offer.

Instead, the relevant questions are:

  • What loan program is the buyer using?
  • Has the lender reviewed the specific purchase price?
  • Are additional reserves required?
  • Does the loan require additional documentation?
  • Is the proposed closing timeline realistic?

The financing structure should already make sense for the specific Star Trail property before the seller accepts the offer.

The Appraisal Is a Separate Risk From Loan Approval

A buyer can be financially well qualified and the transaction can still encounter an appraisal issue.

The lender typically wants independent support for the value of the property being financed.

If the appraisal is below the contract price, possible outcomes may include:

  • The buyer bringing additional cash.
  • The parties renegotiating the price.
  • A combination of additional buyer cash and seller adjustment.
  • The transaction continuing under terms already negotiated in the contract.
  • The contract becoming subject to applicable appraisal provisions.

The exact outcome depends on the contract terms and the buyer’s financial flexibility.

Appraisal Risk Can Matter More When an Offer Is Aggressive

An offer substantially above recent comparable sales may look attractive, but the seller should consider how the buyer intends to handle a possible appraisal gap.

Important questions include:

  • Does the buyer have additional cash?
  • Has the buyer agreed to cover any appraisal difference?
  • Is there a limit to that commitment?
  • What appraisal protections are included in the contract?

An unusually high offer is only valuable if the buyer can actually complete the purchase under the agreed terms.

Buyer Financing Can Affect the Closing Timeline

A financed transaction generally requires enough time for:

  • Loan processing.
  • Underwriting.
  • Appraisal.
  • Final document review.
  • Verification of buyer funds.
  • Lender approval for closing.

A very short closing period may sound attractive to a seller, but it should also be realistic for the buyer’s lender and loan program.

An unrealistic closing date can create extensions and uncertainty later.

Financing Approval Can Change During the Contract Period

Loan approval is not always static.

Before closing, lenders may continue reviewing:

  • Employment.
  • Income.
  • Assets.
  • Credit.
  • Debt obligations.
  • Property-related conditions.

A buyer who takes on new debt, changes employment or encounters another financial issue can potentially create complications even after receiving an initial approval.

This is one reason sellers should value strong qualification from the beginning.

Interest-Rate Changes Can Affect Buyer Qualification

Mortgage rates can change while a buyer is searching for a home or moving through the loan process.

A change in rate can affect:

  • Monthly payment.
  • Debt-to-income calculations.
  • Buyer purchasing power.
  • Loan approval.

Sellers do not need to become mortgage experts, but they should understand whether the buyer’s lender has accounted for the proposed transaction and whether the financing appears stable.

Seller Concessions Can Affect Your Net Proceeds

A buyer may request that the seller contribute toward certain allowable closing expenses.

The seller should evaluate the request as part of the complete offer rather than looking only at the headline purchase price.

For example, an offer with a higher price but a substantial seller credit may produce a lower seller net than an offer with a slightly lower price and no requested credit.

Always compare the estimated net result of competing offers.

Learn About Seller Closing Costs and Net Proceeds

Lender Rules Can Limit Some Seller Concessions

Seller concessions are also subject to the buyer’s loan program and lender requirements.

The amount and type of allowable credit can vary depending on factors such as:

  • Loan program.
  • Down payment.
  • Occupancy.
  • Lender guidelines.
  • The buyer’s actual allowable closing expenses.

Because the rules can vary, concession terms should be coordinated with the buyer’s lender before the seller assumes a particular credit can be used exactly as proposed.

Financing and Inspection Risk Are Different

A financially strong buyer can still request repairs after an inspection.

Likewise, a home in excellent condition can still encounter financing or appraisal issues.

When comparing offers, sellers should consider several separate categories of risk:

  • Financing.
  • Appraisal.
  • Inspection.
  • Buyer cash position.
  • Closing timeline.
  • Contract contingencies.

No single term tells the complete story.

Financing Deadlines Matter After the Offer Is Accepted

Once under contract, the transaction moves through a series of deadlines and lender requirements.

Seller attention may shift to:

  • Financing approval.
  • Appraisal completion.
  • Inspection negotiations.
  • Title work.
  • HOA documentation.
  • Contract amendments.
  • Closing coordination.

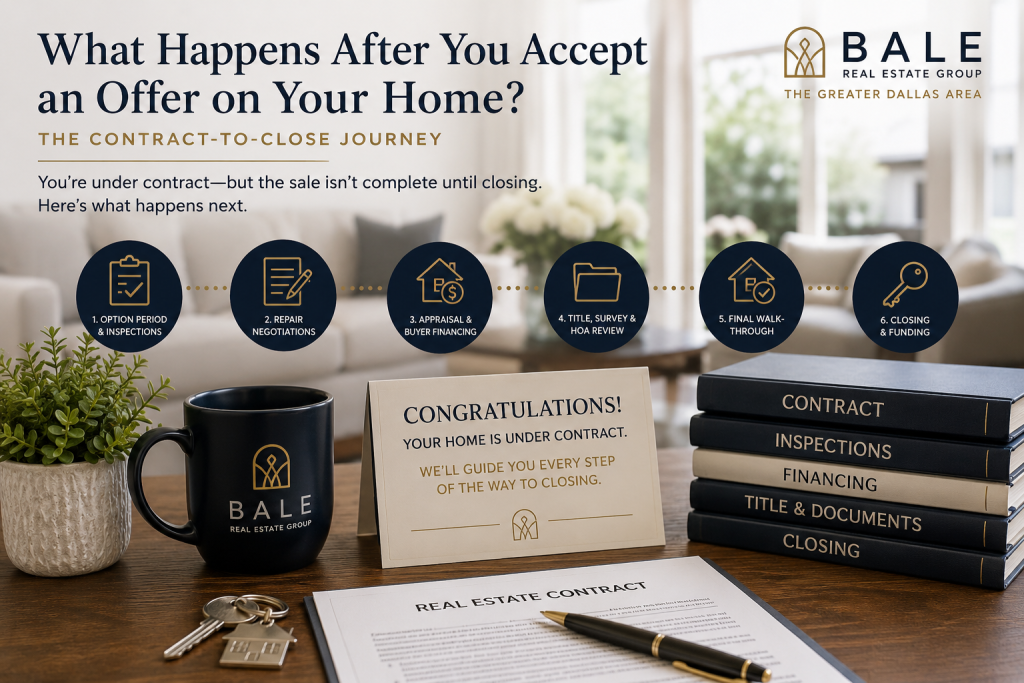
What Happens After You Accept an Offer on Your Home?

What If the Buyer’s Financing Is Delayed?

A financing delay does not automatically mean the transaction will fail.

The important questions are:

  • What caused the delay?
  • Has the lender identified a specific solution?
  • How much additional time is required?
  • Are all other buyer obligations being completed?
  • Does extending the contract still serve the seller’s goals?

A seller considering an extension should evaluate the circumstances carefully rather than assuming every delay deserves the same response.

What If the Buyer Cannot Obtain Financing?

The answer depends on the contract and the circumstances surrounding the financing failure.

Possible consequences may be affected by:

  • The financing provisions in the contract.
  • Applicable deadlines.
  • Notices delivered by the buyer.
  • Earnest-money provisions.
  • Other negotiated terms.

Contract rights and obligations should be evaluated based on the actual documents involved in the transaction.

Cash Offers Should Still Be Evaluated Carefully

A cash offer removes lender underwriting and loan approval from the transaction, but it should not automatically be assumed to be the best offer.

A seller should still evaluate:

  • Price.
  • Proof of funds.
  • Inspection terms.
  • Appraisal provisions, if any.
  • Closing date.
  • Contingencies.
  • Other seller costs.

Cash can reduce financing uncertainty, but price and contract terms still matter.

How Should a Star Trail Seller Compare Multiple Offers?

A useful comparison should evaluate each offer across the same categories.

  • Purchase price.
  • Estimated seller net.
  • Loan type.
  • Down payment.
  • Available buyer cash.
  • Lender strength.
  • Financing protections.
  • Appraisal exposure.
  • Inspection terms.
  • Seller concessions.
  • Closing timeline.
  • Overall probability of closing.

This is why the best offer is not always the offer with the largest number at the top.

Why Star Trail Sellers Choose Bale Real Estate Group

Bale Real Estate Group helps homeowners analyze the complete structure of an offer, including price, financing, appraisal exposure, concessions, contract terms and likely seller net.

Bale Real Estate Group has completed more than $65 million in residential real estate volume and more than 110 successful transactions during the past 48 months while representing buyers and sellers throughout Frisco, Plano, Prosper, McKinney, Allen, Preston Hollow, and surrounding North Texas communities.

Ranked among the top 1% of North Texas Realtors, Bale Real Estate Group has also earned more than 80 five-star client reviews.

Why Sellers Hire Bale Real Estate Group
Meet the Team

What Seller Clients Say

“She worked hard to secure the best possible outcome for me, carefully reviewing every offer, explaining my options, and negotiating strategically to maximize the value of my home.”

— Debbie Willet, 5-Star Client Review

“They guided us on pricing, helped us navigate offers, and made sure we were protected every step of the way. We truly felt like we had someone in our corner who knew the market and knew how to get results.”

— Brian Brignac, 5-Star Client Review

“Linda kept us consistently informed about market trends and strategically used that information to justify the market price, gathered feedback from showings, and ensured we felt confident in every decision.”

— Laura Donovan, 5-Star Client Review

Read More Client Testimonials

Other Prosper Communities to Consider

Windsong Ranch — A large Prosper master-planned community known for extensive amenities and a broad range of newer homes.
Gentle Creek — An established Prosper community known for substantial homes, larger lots and golf-course settings.
Whitley Place — A Prosper luxury community offering larger homes, distinctive residential settings and mature surroundings.
Saddle Creek — An established Prosper community offering substantial homes, pools and varied residential settings.
Lakes of La Cima — An established Prosper community offering substantial homes and a broad range of property styles.

Frequently Asked Questions About Buyer Financing for Star Trail Sellers

Should I accept the highest offer on my Star Trail home?

Not automatically. Sellers should compare price with financing strength, appraisal exposure, concessions, inspection terms, closing timeline and the probability of reaching closing.

How important is a buyer’s preapproval?

Very important. A stronger preapproval can provide more confidence that the buyer’s income, credit, assets and proposed financing have already received meaningful lender review.

Does a larger down payment make an offer stronger?

It can provide additional financial flexibility, but the entire offer should still be evaluated. Loan approval, lender quality, appraisal terms and buyer cash reserves also matter.

Can an appraisal affect a financed offer?

Yes. If an appraisal is below the contract price, the buyer and seller may need to rely on the appraisal terms already negotiated in the contract or reach a new agreement.

Should I prefer a cash buyer?

Cash removes lender underwriting risk, but it does not automatically make the offer superior. Price, proof of funds, inspection terms, contingencies and closing timing still matter.

Can a seller contribute toward the buyer’s closing costs?

Potentially. Seller concessions can be negotiated, but allowable amounts and uses may depend on the buyer’s loan program and lender requirements.

What happens after I accept a financed offer?

The buyer typically moves through loan processing, appraisal, underwriting and final lender approval while the transaction also proceeds through inspections, title, HOA requirements and other contract deadlines.

Have a Financed Offer on Your Star Trail Home?

Bale Real Estate Group can help Star Trail homeowners compare the full strength of an offer, including financing, appraisal exposure, seller concessions, closing timing and estimated net proceeds.

The goal is not simply to accept an offer. It is to choose terms that provide a strong combination of value and closing confidence.

Clarity First. Pressure Never.

Explore Seller Services

Why Sellers Hire Bale Real Estate Group

Meet the Team

Schedule a Pre-Listing Appointment

Contact Bale Real Estate Group

Posted in: Uncategorized Tagged: #BuyerFinancing, #HomeSelling, #ProsperRealEstate, #ProsperTX, #SellerTips, #StarTrail, #StarTrailProsper

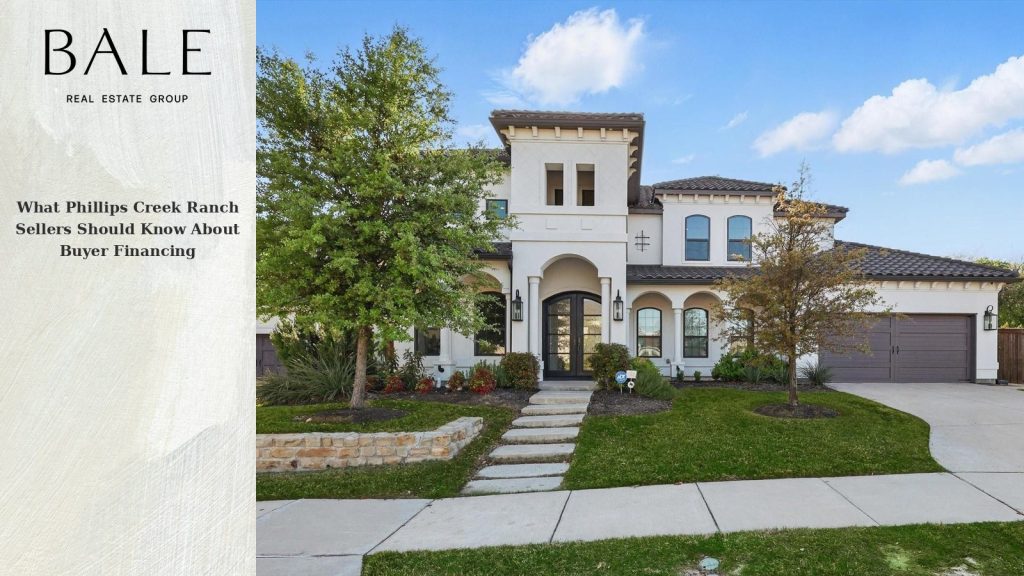
What Phillips Creek Ranch Sellers Should Know About Buyer Financing

Buyer financing for Phillips Creek Ranch sellers

When a Phillips Creek Ranch seller receives a financed offer, the purchase price is only one part of deciding how strong that offer really is.

The buyer’s loan type, lender preparation, down payment, available funds, requested concessions, appraisal exposure and financing deadlines can all affect the likelihood that the transaction reaches closing.

A financed offer can be very strong. A cash offer can still contain terms that make it less attractive.

The better question is not simply “Is this buyer financing the purchase?” It is “How strong is the complete offer, and how much financing risk does the seller actually have?”

Learn About Seller Offer Strategy and Protection

See the Phillips Creek Ranch Market the Buyer Is Entering

Current competition can affect how a seller weighs price, financing strength and negotiating leverage.

8272 Haltered Horse Lane Frisco TX 75036
New Listing – 4 days on site
1 / 39
$549,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
3
BEDS
2
TOTAL BATHS
2,181
SQFT
8272 Haltered Horse Lane
Frisco, TX 75036
Phillips Creek Ranch Ph 2 Subdivision
878 Gaited Trail Frisco TX 75036
New Listing – 4 days on site
1 / 39
$799,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,483
SQFT
878 Gaited Trail
Frisco, TX 75036
Phillips Creek Ranch Ph 2 Subdivision
965 Touchstone Road Frisco TX 75036
Open House Mon, Sep 14, 9 AM
Please verify times due to COVID-19
1 / 21
$835,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
4,000
SQFT
965 Touchstone Road
Frisco, TX 75036
Phillips Creek Ranch Ph 4b Subdivision
8218 Haltered Horse Lane Frisco TX 75036
1 / 25
$599,900
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence
Pending
4
BEDS
3
TOTAL BATHS
2,643
SQFT
8218 Haltered Horse Lane
Frisco, TX 75036
Phillips Creek Ranch Ph 2 Subdivision
2494 Bunnels Fork Road Frisco TX 75036
1 / 20
$1,100,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,847
SQFT
2494 Bunnels Fork Road
Frisco, TX 75036
Phillips Creek Ranch Riverton Subdivision
764 Thoroughbred Avenue Frisco TX 75036
Price Change – 5 days ago
1 / 35
$940,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
3,587
SQFT
764 Thoroughbred Avenue
Frisco, TX 75036
Phillips Creek Ranch Silvertai Subdivision
967 Cimarron Road Frisco TX 75036
Price Change – 4 days ago
1 / 34
$1,849,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
5,636
SQFT
967 Cimarron Road
Frisco, TX 75036
Phillips Creek Ranch Ph 7-A Subdivision
7264 Nichols Trail Frisco TX 75036
1 / 40
$1,000,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
4
TOTAL BATHS
3,959
SQFT
7264 Nichols Trail
Frisco, TX 75036
Phillips Creek Ranch Ph 1 Subdivision
852 Sweet Iron Road Frisco TX 75036
Price Change – 2 weeks ago
1 / 35
$790,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
4
TOTAL BATHS
3,458
SQFT
852 Sweet Iron Road
Frisco, TX 75036
Phillips Creek Ranch Ph 2 Subdivision
8036 Sylvan Dale Road Frisco TX 75036
1 / 37
$649,900
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence
Pending
4
BEDS
4
TOTAL BATHS
2,913
SQFT
8036 Sylvan Dale Road
Frisco, TX 75036
Phillips Creek Ranch Ph 2 Subdivision
6448 Fire Creek Trail Frisco TX 75036
1 / 30
$895,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
3
TOTAL BATHS
3,267
SQFT
6448 Fire Creek Trail
Frisco, TX 75036
Phillips Creek Ranch Sheridan Subdivision
689 Dancing Water Drive Frisco TX 75036
1 / 40
$1,749,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
7
TOTAL BATHS
5,353
SQFT
689 Dancing Water Drive
Frisco, TX 75036
Phillips Creek Ranch Ph 7-A Subdivision
625 Quarter Horse Lane Frisco TX 75036
Price Change – 3 weeks ago
1 / 38
$885,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
4
TOTAL BATHS
3,531
SQFT
625 Quarter Horse Lane
Frisco, TX 75036
Phillips Creek Ranch Silvertai Subdivision
5588 Highflyer Hills Trail Frisco TX 75036
1 / 40
$1,089,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,083
SQFT
5588 Highflyer Hills Trail
Frisco, TX 75036
Phillips Creek Ranch Ph 4b Subdivision
417 Carlsbad Drive Frisco TX 75036
1 / 40
$1,890,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
5
TOTAL BATHS
4,623
SQFT
417 Carlsbad Drive
Frisco, TX 75036
Phillips Creek Ranch Ph 7-C Subdivision
6616 Mountain Sky Road Frisco TX 75036
Price Change – 5 days ago
1 / 39
$1,175,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
5
BEDS
6
TOTAL BATHS
4,829
SQFT
6616 Mountain Sky Road
Frisco, TX 75036
Phillips Creek Subdivision
5630 Highflyer Hills Trail Frisco TX 75036
1 / 39
$785,000
IDX Logo for North Texas Real Estate Information Systems
Single Family Residence For Sale
Active
4
BEDS
4
TOTAL BATHS
2,630
SQFT
5630 Highflyer Hills Trail
Frisco, TX 75036
Phillips Creek Ranch Ph 4b Subdivision

A Pre-Approval Letter Is a Starting Point—not a Guarantee

A lender letter can show that a buyer has begun the financing process, but it does not guarantee final loan approval.

After the contract is signed, the lender may continue reviewing:

  • Income.
  • Employment.
  • Assets.
  • Credit.
  • Debt obligations.
  • The property.
  • The appraisal when required.
  • Other underwriting conditions.

Sellers should understand how much lender review has occurred rather than treating every pre-approval letter as identical.

Ask How Thoroughly the Buyer Has Been Reviewed

Before accepting a financed offer, useful questions may include:

  • Has the lender reviewed income documentation?
  • Have assets needed for closing been reviewed?
  • Has credit been evaluated?
  • Has the buyer completed the lender’s requested application process?
  • Are there known financing conditions that still need to be satisfied?
  • Does the lender believe the proposed closing date is realistic?

The more complete the buyer’s financing preparation is before the offer, the better the seller can evaluate transaction risk.

The Buyer’s Down Payment Is Only One Part of the Financial Picture

A larger down payment can reduce the amount being financed, but it does not automatically make an offer stronger.

A smaller down payment also does not automatically make an offer weak.

The seller should consider the complete situation, including:

  • Total loan amount.
  • Available funds.
  • Requested seller concessions.
  • Appraisal exposure.
  • Lender preparation.
  • The other contractual terms.

Do not judge financing strength from one percentage alone.

Different Loan Programs Can Have Different Requirements

Buyers may use conventional, VA or other financing programs.

Each loan program can have its own underwriting, appraisal, documentation and property requirements.

Sellers should not automatically reject or favor an offer simply because of the loan type.

Evaluate the specific buyer, lender, property, contract terms and financing preparation rather than relying on assumptions about a particular loan program.

Learn More About the Home Loan Process

Appraisal Risk Matters With a Financed Offer

When financing requires an appraisal, the lender generally uses that appraisal as part of evaluating the property for the loan.

An offer substantially above relevant market evidence may therefore create additional uncertainty.

Before accepting the offer, the seller should understand:

  • Whether an appraisal is expected.
  • What the contract says if the appraisal is below the purchase price.
  • Whether the buyer has agreed to address any potential appraisal gap.
  • How much financial flexibility the buyer appears to have.

A high purchase price is less valuable if the financing structure makes that price difficult to complete.

Learn How Appraisals Affect Phillips Creek Ranch Home Sales

Strong Pricing Can Reduce Unnecessary Appraisal Exposure

The seller’s original pricing strategy can affect the financing conversation later.

A contract price supported by relevant recent sales and the home’s individual characteristics may provide a different appraisal risk profile from a price that is difficult to reconcile with market evidence.

Important differences may include:

  • Lot location.
  • Privacy.
  • Floor plan.
  • Condition.
  • Renovations.
  • Pool and outdoor living.

Learn How to Price a Phillips Creek Ranch Home

Seller Concessions Can Change the Economics of the Offer

A financed buyer may request seller contributions toward allowable transaction expenses.

Those requests should be evaluated as part of the offer’s complete financial outcome.

For example, a higher purchase price accompanied by substantial seller concessions may produce lower estimated proceeds than another offer with a slightly lower price and fewer deductions.

The headline purchase price and the seller’s likely net proceeds are not always the same thing.

See What You May Net From Selling Your Phillips Creek Ranch Home

Financing Deadlines Can Affect Seller Risk

A financed contract may include important dates and provisions related to the buyer’s loan.

Those terms should be understood and tracked throughout the transaction.

A seller should know:

  • What financing provisions are included in the contract.
  • What deadlines apply.
  • Whether the buyer is meeting lender requirements on schedule.
  • Whether any financing concern could affect closing.

Financing should be monitored throughout the transaction—not reviewed once when the offer arrives and then forgotten.

The Buyer’s Lender Can Matter

A lender’s communication and preparation can affect how smoothly a financed transaction proceeds.

Important considerations can include:

  • Responsiveness.
  • Familiarity with the buyer’s financial file.
  • Ability to explain the stage of loan review.
  • Realistic expectations about the closing timeline.
  • Timely coordination of appraisal and underwriting requirements.

A strong buyer with an unprepared lending process can create unnecessary transaction uncertainty.

Cash Is Not Automatically Better Than Financing

A cash offer can remove lender-related uncertainty, but the seller still needs to evaluate the complete contract.

A financed offer may provide:

  • A stronger purchase price.
  • Fewer concessions.
  • Better closing timing.
  • More favorable possession terms.
  • A stronger overall financial result.

Meanwhile, a cash offer may still contain lengthy due diligence, significant concessions or other terms that reduce its appeal.

Compare the complete offers rather than using “cash” or “financed” as the deciding factor.

A Higher-Priced Financed Offer Is Not Automatically the Best Offer

When sellers receive multiple offers, it can be tempting to sort them by purchase price and stop there.

A stronger analysis compares:

  • Purchase price.
  • Estimated net proceeds.
  • Buyer financing strength.
  • Appraisal exposure.
  • Seller concessions.
  • Inspection and option terms.
  • Closing date.
  • Possession.
  • Probability of successfully closing.

The strongest offer is the one that provides the best combination of financial outcome, acceptable risk and contractual terms for the seller.

Learn How to Evaluate an Offer on a Phillips Creek Ranch Home

Buyer Financing Can Continue to Change After the Offer Is Accepted

A financing file is not necessarily complete once the contract is signed.

During the contract period, lenders may continue verifying information and requesting additional documentation from the buyer.

Changes involving employment, credit, debt or available funds can potentially affect financing.

This is why continued lender communication and deadline tracking remain important until closing.

Property Condition Can Affect Financing Too

Depending on the loan program and circumstances, certain property conditions may receive attention during the financing or appraisal process.

This does not mean every home needs to be renovated or every older component replaced before accepting a financed offer.

However, known concerns involving condition should be considered alongside the buyer’s loan structure.

For qualifying listings, Bale Real Estate Group can provide a professional pre-listing inspection at our expense through the Certified Pre-Owned Home Listing Program.

What Happens if the Buyer’s Financing Develops a Problem?

The answer depends on the specific contract, financing provisions, deadlines and circumstances.

If a concern develops, important questions can include:

  • What exactly is causing the delay or financing issue?
  • Can the lender provide a realistic solution and timeline?
  • What rights do the buyer and seller have under the contract?
  • Would an extension benefit the seller?
  • What alternatives exist if the transaction cannot proceed?

Do not make assumptions about contractual rights when financing problems arise. Review the actual agreement and obtain appropriate professional guidance when necessary.

Financing Should Be Part of the Contract-to-Closing Strategy

After an offer is accepted, the transaction still requires coordination through appraisal, inspections, lender requirements, title, contractual deadlines and closing.

A financing issue discovered early may provide more options than one discovered immediately before closing.

Learn What Happens After You Accept an Offer on Your Home

Questions Phillips Creek Ranch Sellers Should Ask About Buyer Financing

  • What loan type is the buyer using?
  • How much of the purchase price is being financed?
  • What level of lender review has already occurred?
  • Has the lender reviewed the buyer’s supporting documentation?
  • Are seller concessions being requested?
  • What appraisal exposure exists?
  • What financing-related deadlines apply?
  • Does the lender believe the proposed closing date is realistic?
  • What happens under the contract if financing or appraisal becomes a problem?

The purpose is not to interrogate the buyer. It is to understand the risk attached to the offer before making a major financial decision.

What Seller Clients Say About Bale Real Estate Group

“She worked hard to secure the best possible outcome for me, carefully reviewing every offer, explaining my options, and negotiating strategically to maximize the value of my home.”

— Debbie Willet, Seller Client

“They guided us on pricing, helped us navigate offers, and made sure we were protected every step of the way. We truly felt like we had someone in our corner who knew the market and knew how to get results.”

— Brian Brignac, Seller Client

“Their expertise, responsiveness, and genuine care turned a potentially stressful process into a smooth and successful experience. Thanks to their efforts, we were able to successfully sell our home at our price.”

— Minesh Patel, Seller Client

Read More Client Testimonials

Frequently Asked Questions About Buyer Financing for Phillips Creek Ranch Sellers

Is a cash offer always stronger than a financed offer?

No. Cash can reduce lender-related uncertainty, but purchase price, concessions, due diligence, timing, possession and the complete contract still need to be compared.

Does a pre-approval guarantee the buyer will get the loan?

No. Loan approval can remain subject to underwriting, property requirements and other lender conditions after the offer is accepted.

Should I avoid a buyer using a certain type of loan?

Not automatically. Evaluate the specific buyer, lender preparation, financing structure, property requirements and complete offer rather than relying on assumptions about the loan type.

Why does the seller care about the buyer’s lender?

The lender’s preparation and responsiveness can affect appraisal coordination, underwriting, financing deadlines and the proposed closing date.

Can seller concessions affect which offer is strongest?

Yes. Concessions can reduce estimated seller proceeds, so they should be included when comparing the economics of competing offers.

What happens if the appraisal is lower than the contract price?

The outcome depends on the contract terms, financing structure and decisions of the parties. Sellers should understand the appraisal provisions before accepting the offer.

Can buyer financing fail after we are under contract?

It can. Financing may remain subject to lender underwriting and other requirements until the transaction is completed.

Should I accept the highest-priced financed offer?

Not automatically. Compare estimated proceeds, financing strength, appraisal exposure, contractual terms and likelihood of closing along with the purchase price.

Evaluating a Financed Offer on Your Phillips Creek Ranch Home?

Do not evaluate the loan separately from the rest of the contract.

Bale Real Estate Group can help sellers compare purchase price, estimated proceeds, financing strength, concessions, appraisal exposure, timing and other offer terms before making a decision.

Bale Real Estate Group has completed more than $65 million in residential real estate volume and more than 110 successful transactions during the past 48 months while representing buyers and sellers throughout Frisco, Plano, Prosper, McKinney, Allen, Preston Hollow, and surrounding North Texas communities.

Bale Real Estate Group ranks among the top 1% of North Texas Realtors and has earned more than 80 five-star client reviews.

Learn How to Evaluate an Offer

Explore Seller Offer Strategy and Protection

Contact Bale Real Estate Group

Clarity First. Pressure Never.

Posted in: Uncategorized Tagged: #BuyerFinancing, #FriscoRealEstate, #FriscoTX, #HomeSelling, #PhillipsCreekRanch

What Happens After You Accept an Offer on Your Home?

Accepting an offer is an important milestone, but the home sale is not finished until closing and funding.

Many sellers ask what happens after they accept an offer on their home. The answer depends on the contract terms, option period, inspections, appraisal, buyer financing, title work, HOA requirements, repair negotiations, lender deadlines, and closing timeline.

This stage is commonly called contract-to-close.

Gary and Linda Bale with Bale Real Estate Group help homeowners throughout Allen, Aubrey, Celina, Coppell, Dallas, Frisco, McKinney, Park Cities, Plano, Preston Hollow, Princeton, Prosper, North Dallas, and the surrounding Greater Dallas area stay organized, understand deadlines, evaluate inspection issues, monitor buyer financing, and move toward closing with confidence.

Why Contract-to-Close Matters

Getting under contract is only part of the selling process.

After an offer is accepted, several important steps still need to occur before the transaction is complete.

These may include:

• Earnest money delivery
• Option fee delivery
• Buyer inspections
• Repair negotiations
• Appraisal
• Buyer financing approval
• Title review
• Survey review
• HOA document review, when applicable
• Seller disclosures and documents
• Closing statement review
• Final walk-through
• Closing and funding

A strong contract-to-close process helps reduce confusion, protect deadlines, and keep the transaction moving.

Step 1: Earnest Money and Option Fee

After the contract is signed, the buyer typically has deadlines to deliver earnest money and the option fee.

Earnest money demonstrates the buyer’s good faith and is generally held by the title company.

The option fee gives the buyer the right to terminate during the negotiated option period, subject to the terms of the contract.

Sellers should confirm that both items are delivered on time and properly documented.

Step 2: The Option Period

The option period is one of the most important stages of the contract.

During this time, the buyer may inspect the property, review its condition, evaluate possible repairs, and decide whether to continue with the purchase.

The buyer may:

• Complete a general home inspection
• Inspect the roof
• Inspect the pool, when applicable
• Review structural and mechanical systems
• Request repairs or credits
• Renegotiate certain terms
• Terminate when permitted by the contract

Seller preparation and experienced guidance matter during this stage.

Learn more about home inspections and repair negotiations for sellers.

Step 3: Repair Negotiations

After the inspection, the buyer may submit a repair request.

The seller is not automatically required to agree to every item.

Repair negotiations should be evaluated based on:

• Contract terms
• Inspection findings
• Seriousness of the concern
• Buyer expectations
• Current market conditions
• Seller priorities
• Estimated repair costs
• Closing timeline
• Risk of the buyer terminating
• Risk of returning to the market

Bale Real Estate Group helps sellers evaluate repair requests strategically rather than emotionally.

The goal is to protect the transaction while avoiding unnecessary concessions.

Step 4: Appraisal and Buyer Financing

When the buyer is using financing, the lender generally orders an appraisal.

The appraisal helps the lender determine whether the property supports the loan amount.

If the appraisal is lower than the contract price, the buyer and seller may need to renegotiate unless the buyer has agreed to cover some or all of the difference.

Buyer financing also needs to progress through:

• Income and asset verification
• Credit review
• Loan underwriting
• Property appraisal
• Final loan approval
• Closing disclosure requirements
• Funding preparation

Learn more about appraisals and buyer financing when selling your home.

Step 5: Title, Survey, and HOA Documents

The title company plays a major role after the contract is signed.

The title process may include reviewing:

• Ownership records
• Existing liens
• Mortgage payoffs
• Property taxes
• Title commitments
• Easements and restrictions
• Closing documents
• Funding requirements

Depending on the transaction, the buyer, lender, and title company may also review the property survey.

For homes in an HOA community, resale certificates, governing documents, fees, assessments, and association information may need to be ordered and reviewed.

Delays involving title, surveys, or HOA documents can affect the closing timeline, so organization matters.

Step 6: Seller Responsibilities Before Closing

Sellers may need to complete several items before closing.

These may include:

• Completing agreed repairs
• Providing repair receipts when required
• Maintaining the property’s condition
• Keeping utilities on through closing
• Continuing lawn and pool maintenance
• Coordinating move-out timing
• Reviewing closing documents
• Responding to title requests
• Preparing keys, remotes, and access items
• Removing personal property
• Leaving the home in the agreed condition
• Preparing for the buyer’s final walk-through

A clear checklist helps prevent last-minute problems.

Step 7: Maintain the Home Until Closing

The home should be maintained throughout the contract period.

Sellers should continue:

• Lawn care
• Pool service
• HVAC operation
• Cleaning
• Pest control when needed
• Utility service
• Property insurance
• Security and access control

Damage or a material change in the property’s condition before closing can create serious issues.

The home should remain in substantially the same condition as when the contract was signed, subject to negotiated repairs and normal wear.

Step 8: Final Walk-Through

Before closing, the buyer usually completes a final walk-through.

The purpose is to confirm that:

• The property remains in the agreed condition
• Negotiated repairs were completed
• Included items remain in the home
• Personal property has been removed as agreed
• No material damage has occurred
• The home is ready for possession

Sellers should make sure the property is clean, accessible, secure, and prepared for the buyer’s review.

Step 9: Closing and Funding

Closing is when the seller signs the required documents and the buyer completes the purchase and loan paperwork.

In Texas, signing documents does not always mean the transaction is complete.

The sale is generally complete after the title company receives the required funds, confirms funding, and authorizes the release of ownership and keys according to the contract terms.

The final stage should be coordinated carefully among:

• The title company
• The buyer’s lender
• The buyer’s agent
• The seller’s agent
• The buyer
• The seller

What Can Delay Closing?

Several issues can delay or threaten closing.

Common causes include:

• Inspection disputes
• Incomplete repairs
• Low appraisal
• Buyer financing delays
• Missing lender documents
• Title problems
• Survey concerns
• HOA-document delays
• Insurance issues
• Incomplete seller paperwork
• Final walk-through concerns
• Funding delays

Not every delay can be avoided, but strong communication and early preparation can reduce the risk.

Why Communication Matters After Accepting an Offer

The contract-to-close period can move quickly.

Deadlines matter, and even small delays can create unnecessary stress.

Strong communication helps sellers understand:

• What has been completed
• What remains pending
• Which deadlines are approaching
• Which documents are needed
• What the buyer is requesting
• Whether financing is progressing
• Whether title has identified concerns
• Whether the appraisal has been completed
• When closing and funding are expected

Gary and Linda Bale help sellers stay informed from accepted offer through closing so they are not left guessing.

How Preparation Before Listing Helps Contract-to-Close

A smoother contract-to-close process often begins before the property is listed.

Pre-listing preparation can help reduce buyer concerns, inspection surprises, and negotiation stress.

Helpful preparation may include:

• A Pre-Listing Appointment
• Home value review
• Market-based pricing strategy
• Cleaning and decluttering
• Repair review
• Professional photography preparation
• Pre-listing inspection when appropriate
• The Certified Pre-Owned Home Listing Program

Learn more about what to do before listing your home for sale.

Featured Communities and Areas We Serve

Bale Real Estate Group helps homeowners prepare, price, market, negotiate, and close home sales throughout Allen, Aubrey, Celina, Coppell, Dallas, Frisco, McKinney, Park Cities, Plano, Preston Hollow, Princeton, Prosper, North Dallas, and the surrounding Greater Dallas area.

The communities below are featured on our website because of our experience, local knowledge, and ongoing marketing in these areas. However, our seller services are not limited to these neighborhoods. We help homeowners throughout the Greater Dallas area from preparation and pricing through closing and funding.

Featured Frisco Communities

• Chapel Creek
• Country Club Ridge at The Trails
• Custer Creek Farms
• Edgestone at Legacy
• Griffin Parc
• Heather Ridge Estates
• Newman Village
• Park Place Estates
• Phillips Creek Ranch
• Richwoods
• Shaddock Creek Estates
• Starwood
• Stonebriar
• The Canals at Grand Park
• The Fairways
• The Hills of Kingswood
• Villages of Stonebriar Park

Featured Plano Communities

• Avignon Windhaven
• Cliffs of Gleneagles
• Crystal Creek
• Deerfield
• Kings Gate
• Lakeside on Preston
• Normandy Estates
• Shoal Creek
• Wentworth Estates
• Willow Bend
• Willow Bend Polo Estates
• Windrose Tower

Additional Greater Dallas Areas We Support

• Allen
• Aubrey
• Celina
• Coppell
• Dallas
• McKinney
• Park Cities
• Princeton
• Prosper

Featured Dallas and North Dallas Communities

• Oakdale
• Preston Hollow

Helpful Videos for Sellers

Zillow Showcase Program

Elevating the Luxury Home-Selling Experience

Certified Pre-Owned Home Listing Program

Why Are So Many People Moving to Frisco, Texas?

Why Are So Many People Moving to Plano, Texas?

Frequently Asked Questions About Contract-to-Close

What happens after I accept an offer on my home?

After accepting an offer, the buyer typically delivers earnest money and the option fee, completes inspections, works through financing and appraisal, reviews title and HOA documents when applicable, completes a final walk-through, and proceeds to closing and funding.

Is the home sold once I accept an offer?

No. The home is under contract, but the sale is not complete until all contract requirements are satisfied and the transaction closes and funds.

What is the option period?

The option period is a negotiated period during which the buyer may inspect the home, request repairs, renegotiate certain terms, or terminate when permitted by the contract.

Does the seller have to agree to every repair request?

No. Repair requests are negotiable. The seller should evaluate the contract, inspection findings, market conditions, costs, buyer strength, and risk of termination before responding.

What happens if the appraisal is low?

The buyer and seller may need to renegotiate, the buyer may bring additional cash, the seller may reduce the price, or the transaction may be affected depending on the financing addendum and contract terms.

What can delay closing?

Closing may be delayed by inspection disputes, appraisal issues, financing problems, title concerns, survey issues, HOA-document delays, incomplete repairs, missing paperwork, or funding delays.

Should utilities stay on until closing?

Yes, in most cases. Utilities should remain on through closing so inspections, repairs, the final walk-through, and lender requirements can be completed.

When should the seller release the keys?

Keys should be released according to the contract and title company instructions, generally after funding unless a different possession arrangement has been negotiated.

How can sellers make contract-to-close smoother?

Sellers can help by preparing before listing, responding quickly, keeping the home maintained, completing agreed repairs, monitoring deadlines, keeping utilities on, and working with a Realtor who manages the process carefully.

Ready for a Smoother Selling Process?

If you are considering selling in Allen, Aubrey, Celina, Coppell, Dallas, Frisco, McKinney, Park Cities, Plano, Preston Hollow, Princeton, Prosper, North Dallas, or another Greater Dallas community, the best place to start is with a Pre-Listing Appointment.

You do not need to live in one of our featured communities to work with Bale Real Estate Group. We help sellers throughout the Greater Dallas area understand their home’s value, prepare for the market, develop the right pricing strategy, evaluate offers, manage inspections and financing, and move from contract to closing with clear communication.

There is no pressure. The goal is to help you understand your home’s value, preparation options, pricing strategy, marketing plan, offer terms, and what to expect from listing through closing.

Learn more about Gary and Linda Bale, read our client testimonials, and see why homeowners hire Bale Real Estate Group to sell their homes.

Posted in: Seller Resources Tagged: #AcceptedOffer, #Appraisal, #BuyerFinancing, #ClosingDay, #ContractToClose, #FriscoRealEstate, #HomeInspection, #PlanoRealEstate, #SellingAHome

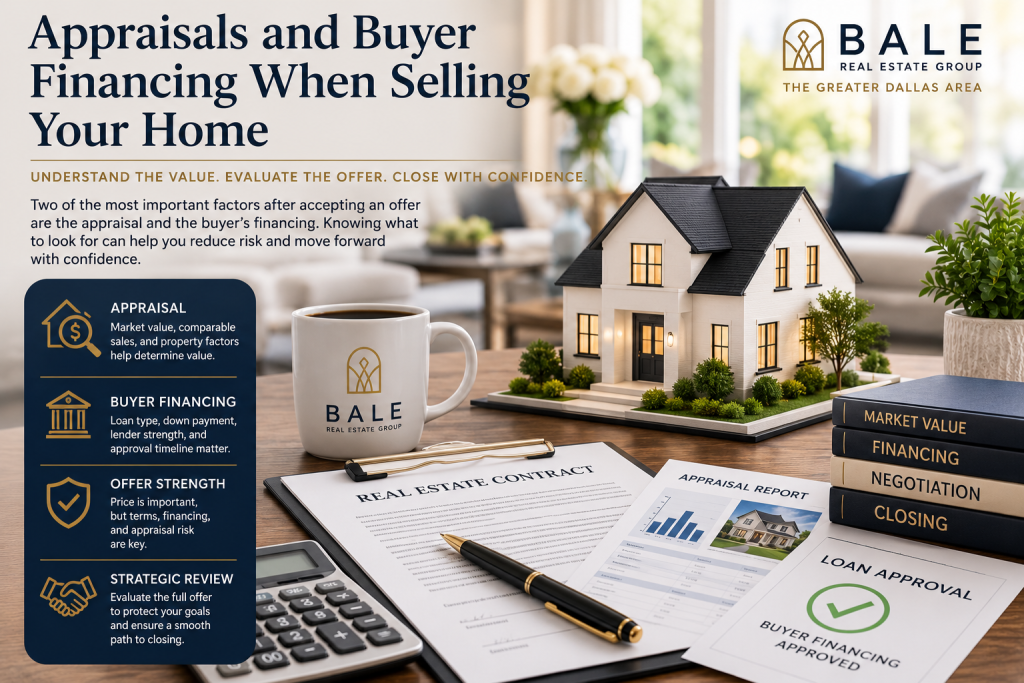
What Sellers Should Know About Appraisals and Buyer Financing

If you are selling your home, accepting an offer is an important step, but the transaction still has to make it to closing.

Two of the most important issues after accepting an offer are the appraisal and the buyer’s financing.

Understanding appraisals and buyer financing when selling your home can help you evaluate offers more carefully, reduce risk, and avoid surprises during the contract period.

Gary and Linda Bale with Bale Real Estate Group help homeowners throughout Allen, Aubrey, Celina, Coppell, Dallas, Frisco, McKinney, Park Cities, Plano, Preston Hollow, Princeton, Prosper, North Dallas, and the surrounding Greater Dallas area review offers, evaluate lender strength, understand appraisal risk, negotiate strategically, and move toward closing with confidence.

Why Appraisals Matter When Selling a Home

When a buyer is using financing, the lender usually requires an appraisal.

The appraisal helps the lender determine whether the property supports the requested loan amount. Even if the buyer is willing to pay the contract price, the lender wants to confirm that the home’s value supports the financing.

If the appraisal comes in below the contract price, the transaction may need to be renegotiated unless the buyer has the ability and willingness to cover the difference.

That is why sellers should understand appraisal risk before accepting an offer.

What Can Affect an Appraisal?

An appraiser may consider:

• Recent comparable sales
• Neighborhood activity
• Property condition
• Square footage
• Lot size
• Updates and improvements
• Pool and outdoor living features
• Location
• Age of the home
• Market trends
• Contract price
• Comparable active and pending listings

For luxury homes, appraisals can be more complicated because comparable sales may be limited.

This is especially true in:

• Custom-home neighborhoods
• Gated communities
• Golf-course communities
• Areas with large differences in lot size
• Communities with a wide range of finish levels
• Neighborhoods with both renovated and original-condition homes

A home may be worth more to a buyer because of design, setting, privacy, or lifestyle features, but the appraiser still needs market data to support the lender’s valuation.

Why Buyer Financing Strength Matters

Not all offers are equal.

A high offer may look attractive, but sellers also need to understand whether the buyer is financially strong enough to close.

Before accepting an offer, sellers should evaluate:

• Buyer loan type
• Down-payment amount
• Pre-approval strength
• Lender reputation
• Appraisal risk
• Financing contingencies
• Earnest money
• Option period
• Closing timeline
• Buyer’s ability to cover an appraisal gap
• Overall certainty of closing

Bale Real Estate Group helps sellers review the complete offer, not just the offer price.

The Highest Offer Is Not Always the Best Offer

The highest offer may not be the strongest offer.

A slightly lower offer with stronger financing, a larger down payment, stronger lender communication, a shorter option period, or better appraisal protection may be more attractive than a higher offer with significantly more risk.

Sellers should compare:

• Price
• Financing strength
• Appraisal risk
• Option period
• Earnest money
• Contingencies
• Closing date
• Leaseback needs
• Repair expectations
• Buyer flexibility
• Probability of closing

The goal is not only to get under contract. The goal is to reach closing and funding.

Review the Buyer’s Loan Type

Different loan types can create different considerations for sellers.

The buyer may be using:

• Conventional financing
• Jumbo financing
• FHA financing
• VA financing
• Portfolio financing
• Cash combined with financing
• Another specialized loan program

Each loan type may have different appraisal, property-condition, underwriting, documentation, and timing requirements.

The loan type does not automatically make an offer strong or weak. The full financial picture, lender quality, buyer qualifications, and contract terms matter.

What Is an Appraisal Gap?

An appraisal gap is the difference between the contract price and the appraised value.

For example, if a home is under contract for $1,000,000 but appraises for $950,000, the appraisal gap is $50,000.

The buyer may agree in advance to cover some or all of that difference with additional cash.

Appraisal-gap terms should be reviewed carefully because the language can affect:

• How much the buyer must contribute
• Whether the buyer can renegotiate
• Whether the seller must reduce the price
• Whether the buyer has a right to terminate
• How much financial risk each party is accepting

A verbal promise is not enough. Appraisal protection should be addressed clearly in the contract and related addenda.

What Happens if the Appraisal Comes in Low?

If the appraisal comes in below the contract price, several outcomes are possible.

The buyer may:

• Ask the seller to reduce the price
• Bring additional cash to closing
• Renegotiate the terms
• Challenge or appeal the appraisal
• Cancel when permitted by the contract
• Explore another loan option when available

The seller may:

• Hold firm on price
• Agree to a price adjustment
• Negotiate a partial adjustment
• Request a larger buyer contribution
• Evaluate the risk of returning to the market
• Review backup offers when available

The right response depends on:

• Contract terms
• Buyer strength
• Size of the appraisal gap
• Market conditions
• Seller goals
• Carrying costs
• Backup-offer availability
• Risk tolerance
• Likelihood of another buyer supporting the price

A low appraisal should be evaluated strategically rather than emotionally.

Can an Appraisal Be Challenged?

In some situations, the buyer’s lender may allow a reconsideration of value.

Supporting information may include:

• More relevant comparable sales
• Recent sales the appraiser did not include
• Corrections to property facts
• Documentation of improvements
• Clarification of square footage
• Evidence of superior lot or location features
• Better neighborhood comparisons

A challenge does not guarantee that the value will change.

The appraiser and lender determine whether the additional information justifies a revision.

Why Pricing Strategy Helps Reduce Appraisal Risk

A strong pricing strategy can help reduce appraisal problems.

If a home is priced well above supportable comparable sales, appraisal risk may increase. This is especially true when the buyer is using financing and has limited additional cash.

Before listing, sellers should understand:

• Recent sold homes
• Active competition
• Pending listings when available
• Condition differences
• Lot and location adjustments
• Updates and improvements
• Days on market
• Buyer demand
• Market momentum
• Likely appraisal support

Learn more about how to price a luxury home to sell.

Why Preparation and Marketing Still Matter

Appraisers focus on market value support, but buyer demand still matters.

A well-prepared and professionally marketed home may attract stronger interest, better offers, and more financially capable buyers.

A customized listing launch may include:

• Pre-listing preparation
• Professional photography
• Drone photography when appropriate
• Video marketing
• Zillow Showcase when the property qualifies
• Detailed listing copy
• MLS and IDX exposure
• Bale Real Estate Group website exposure
• Social media marketing
• Targeted digital advertising
• Community and lifestyle positioning

Learn more about:

Professional Marketing When Selling a Luxury Home
Professional Real Estate Photography
Drone Photography and Aerial Marketing
Zillow Showcase
Why Sellers Hire Bale Real Estate Group

Why Offer Review Should Be Strategic

When an offer arrives, sellers should slow down and review the full picture.

Important questions include:

• Is the buyer fully pre-approved?
• Has the lender been contacted?
• What is the loan type?
• How much is the buyer putting down?
• Is there appraisal-gap protection?
• How much earnest money is offered?
• How long is the option period?
• Are there financing or sale contingencies?
• Does the closing date work?
• Does the buyer need a leaseback?
• Does the offer create unnecessary risk?

A strong offer-review process can help sellers avoid accepting a contract that appears impressive on paper but becomes difficult later.

Seller Financing Concerns to Watch

Potential warning signs may include:

• A weak or incomplete pre-approval
• Limited lender communication
• A very small down payment on a high-priced home
• Unclear appraisal-gap language
• Excessive contingencies
• A long financing timeline
• A buyer who has not supplied requested lender documents
• A lender with limited experience in luxury or jumbo financing
• A buyer whose current home must sell first
• A closing date that does not match lender timing

None of these automatically means the offer should be rejected. They should be reviewed and understood before the seller commits.

Certified Pre-Owned Home Listing Program

Buyer confidence can support stronger offers and a smoother contract period.

The Certified Pre-Owned Home Listing Program is designed to identify potential concerns before the home goes live, reduce surprises during the option period, and help buyers feel more confident when writing an offer.

When buyers have greater confidence in the property’s condition, they may be more comfortable with stronger terms and fewer unknowns.

Appraisal and Financing After the Contract Is Signed

After the seller accepts an offer, the financing process continues.

The buyer may still need to complete:

• Income verification
• Asset verification
• Credit review
• Loan underwriting
• Appraisal
• Insurance approval
• Final lender conditions
• Closing-disclosure review
• Final loan approval
• Funding requirements

A pre-approval is important, but it is not the same as final approval.

That is why ongoing lender communication matters throughout the contract-to-close period.

Learn more about what happens after you accept an offer on your home.

Featured Communities and Areas We Serve

Bale Real Estate Group helps homeowners evaluate offers, appraisal risk, buyer financing, negotiations, and contract-to-close strategy throughout Allen, Aubrey, Celina, Coppell, Dallas, Frisco, McKinney, Park Cities, Plano, Preston Hollow, Princeton, Prosper, North Dallas, and the surrounding Greater Dallas area.

The communities below are featured on our website because of our experience, local knowledge, and ongoing marketing in these areas. However, our seller services are not limited to these neighborhoods. We help homeowners throughout the Greater Dallas area evaluate offers and move from contract to closing.

Featured Frisco Communities

• Chapel Creek
• Country Club Ridge at The Trails
• Custer Creek Farms
• Edgestone at Legacy
• Griffin Parc
• Heather Ridge Estates
• Newman Village
• Park Place Estates
• Phillips Creek Ranch
• Richwoods
• Shaddock Creek Estates
• Starwood
• Stonebriar
• The Canals at Grand Park
• The Fairways
• The Hills of Kingswood
• Villages of Stonebriar Park

Featured Plano Communities

• Avignon Windhaven
• Cliffs of Gleneagles
• Crystal Creek
• Deerfield
• Kings Gate
• Lakeside on Preston
• Normandy Estates
• Shoal Creek
• Wentworth Estates
• Willow Bend
• Willow Bend Polo Estates
• Windrose Tower

Additional Greater Dallas Areas We Support

• Allen
• Aubrey
• Celina
• Coppell
• Dallas
• McKinney
• Park Cities
• Princeton
• Prosper

Featured Dallas and North Dallas Communities

• Oakdale
• Preston Hollow

Helpful Videos for Sellers

Zillow Showcase Program

Elevating the Luxury Home-Selling Experience

Certified Pre-Owned Home Listing Program

Why Are So Many People Moving to Frisco, Texas?

Why Are So Many People Moving to Plano, Texas?

Frequently Asked Questions About Appraisals and Buyer Financing

What happens if my home does not appraise?

If the appraisal comes in below the contract price, the buyer and seller may need to renegotiate. The buyer may bring additional cash, the seller may adjust the price, or the contract may be affected depending on the contract terms and financing addenda.

Is the highest offer always the best offer?

No. Financing strength, appraisal risk, down payment, contingencies, earnest money, option period, lender quality, and closing terms all matter.

How can sellers reduce appraisal risk?

Sellers can reduce appraisal risk by using a thoughtful pricing strategy, reviewing relevant comparable sales, understanding active competition, preparing the home well, and evaluating buyer financing before accepting an offer.

Should sellers verify the buyer’s lender?

Yes. Seller representation should include reviewing the lender, pre-approval strength, loan type, down payment, and potential financing concerns before accepting an offer.

What is appraisal-gap protection?

Appraisal-gap protection is contract language stating that the buyer will cover some or all of the difference between the contract price and the appraised value, subject to the specific terms agreed upon.

Can an appraisal be appealed?

Sometimes. The buyer’s lender may allow a reconsideration of value if there are factual errors or more relevant comparable sales. A change is not guaranteed.

Can a cash offer still have an appraisal?

Yes. A cash buyer may choose to obtain an appraisal for personal information, although a lender would not require one.

Does a large down payment eliminate appraisal risk?

No. A larger down payment may improve financing strength and give the buyer more flexibility, but the contract terms still determine how a low appraisal is handled.

Can professional marketing help with financing or appraisal?

Professional marketing does not replace appraisal support, but it can help attract stronger buyer interest and better offers. Pricing, market data, buyer strength, and comparable sales still matter.

Ready to Review Offers With Confidence?

If you are considering selling in Allen, Aubrey, Celina, Coppell, Dallas, Frisco, McKinney, Park Cities, Plano, Preston Hollow, Princeton, Prosper, North Dallas, or another Greater Dallas community, offer strength, appraisal risk, and buyer financing should be part of your selling strategy.

The best place to start is with a Pre-Listing Appointment so you can understand your home’s value, pricing strategy, preparation options, and likely buyer expectations before the property goes live.

You do not need to live in one of our featured communities to work with Bale Real Estate Group. We help sellers throughout the Greater Dallas area prepare, price, market, review offers, evaluate financing risk, negotiate strategically, and manage the transaction through closing.

There is no pressure. The goal is to help you understand the complete offer, not just the price.

Learn more about Gary and Linda Bale, read our client testimonials, and see why homeowners hire Bale Real Estate Group to sell their homes.

Posted in: Seller Resources Tagged: #AppraisalRisk, #BuyerFinancing, #FriscoRealEstate, #LuxuryHomeSelling, #NorthDallasRealEstate, #OfferReview, #PlanoRealEstate, #SellingAHome

Bale Real Estate Group
972-469-0332
Bale Real Estate Group Best of D 2026 Real Producers 2026 Top Agent eXp Realty
TREC - Information About Brokerage Services
TREC - Consumer Protection Notice
VIEW PRIVACY POLICY
CALL TEXT HOME VALUE
Site created by Michael Tritthart Team. | View Privacy Policy