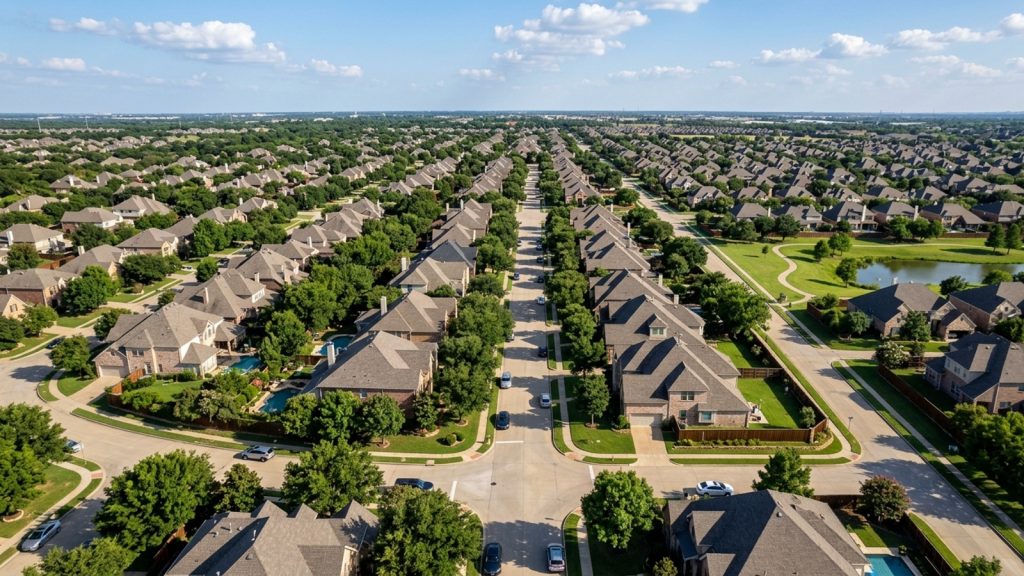
The median home sale price in Plano, TX is sitting around $520,000 right now. That’s a real number, and buying a home in Plano, TX requires a real financial plan before you start touring houses. Homes are spending roughly 37 days on the market before going under contract, which means you don’t have the luxury of figuring out your financing while you shop.
The good news is that Texas has several programs specifically designed to reduce the upfront cash you need to close. If you’re buying in Collin County, you have access to both state and local resources that can cover your down payment, your closing costs, or both.
First-Time Home Buyer Programs Available in Plano
Most of the meaningful assistance available to Plano buyers runs through the state level – specifically through two agencies: the Texas State Affordable Housing Corporation (TSAHC) and the Texas Department of Housing and Community Affairs (TDHCA). These aren’t obscure programs buried in government websites. They’re the main pathways most first-time buyers in Collin County use.
Both agencies work through participating local lenders, pairing competitive interest rates with down payment help. The assistance layers on top of a standard mortgage product, which is how buyers in ZIP codes like 75023, 75024, and 75025 are putting deals together.
State-Level Options
The TDHCA manages the My First Texas Home program, built specifically for buyers who haven’t owned a primary residence in the past three years. TSAHC offers similar loan products aimed at low- and moderate-income buyers across Collin County.
The goal of both is the same: lower the cash barrier at closing. Most borrowers use these programs to supplement their own savings rather than replace them entirely.
Federal Loan Types
State assistance doesn’t stand alone – it’s designed to layer on top of a federal loan. FHA loans are the most common choice for first-time buyers because they allow down payments as low as 3.5%. VA loans offer zero-down financing for eligible veterans and active-duty service members. Your lender will help you determine which underlying mortgage makes sense for your income and credit profile before the state assistance gets stacked on top.
Grants and Down Payment Assistance in Texas
Coming up with the cash to close is almost always the hardest part. The TDHCA’s My First Texas Home program provides up to 5% of the loan amount to apply toward your down payment and closing costs – structured as a 0% interest, no-monthly-payment second lien on the property.
That’s not a small number. On a $400,000 loan, that’s $20,000 you don’t have to pull from savings.
How the Forgivable Lien Works
The 5% assistance is forgiven if you stay in the home as your primary residence for three years. Sell or refinance before that mark, and you repay the full amount. Depending on the specific loan type you choose, the assistance may also be offered as a straight grant with no repayment required at all. Your lender will lay out exactly how the funds are structured during pre-approval.
Applying for Assistance
You don’t apply directly to the TDHCA or TSAHC. You work with a state-approved private lender who processes everything on your behalf. The lender verifies your financials and reserves the assistance funds when you lock your mortgage rate, so the money is ready when you close on your Plano home. It’s a cleaner process than most buyers expect.
Who Qualifies for These Programs
Eligibility comes down to three things: your household income, your credit history, and your first-time buyer status. For the My First Texas Home program, you can’t have owned a primary residence in the prior three years.
Income limits are county-specific. For Collin County in 2026, the TSAHC caps standard household income at $181,650. If you’re buying in a targeted area, that limit rises to $205,870.
Income and Credit Requirements
Lenders will look at your debt-to-income ratio to confirm you can handle the monthly payments. Credit score matters too – the TDHCA requires a minimum of 620 for both its My First Texas Home and My Choice Texas Home programs. That’s not an unusually high bar, but it’s a firm one.
What Disqualifies an Applicant
Earning above $181,650 in a standard area disqualifies you from TSAHC assistance. A credit score below 620 means you’ll need to do some work before applying. Owning an investment property won’t automatically disqualify you, as long as you haven’t owned a primary residence in the last three years. The Plano home you buy with these funds must be your primary residence.
Affording a Home in Plano Right Now
There are currently about 783 homes on the market in Plano. The median sale price is roughly $520,000, and homes are closing at about 97.6% of list price on average. Buyers are coming in close to asking, which means knowing your actual budget before you fall in love with a house matters more than it might in a softer market.
Your monthly payment isn’t just principal and interest – it’s also property taxes, homeowners insurance, and potentially mortgage insurance. You need to know all of it before you start making offers.
The 3-3-3 Rule for Home Buying
The 3-3-3 rule is a straightforward guideline worth knowing: save 3% of the purchase price for a down payment, keep your monthly payment under 33% of your gross income, and hold 3 months of expenses in reserve. Applied to a $300,000 property, you’d be targeting a $9,000 down payment and making sure your gross monthly income comfortably supports the resulting mortgage payment without crossing that 33% threshold.
It’s a blunt instrument, but it keeps buyers from overextending.
Down Payment Examples
A $10,000 down payment on a $300,000 house works out to about 3.3%, which clears the minimum for an FHA loan. At the Plano median of $520,000, a 3.5% down payment is $18,200. If you’re using TDHCA assistance to cover 5% of your loan amount, that money can handle the entire minimum down payment for an FHA or conventional loan – leaving any remaining funds to go toward closing costs.
Tax Credits and Lenders for First-Time Buyers
Down payment help gets most of the attention, but Texas also offers a tax incentive that keeps paying off year after year. The Mortgage Credit Certificate (MCC) lets eligible first-time buyers claim a portion of their mortgage interest as a dollar-for-dollar tax credit – not a deduction, a credit. And you can claim it every year for the life of the loan, as long as the home stays your primary residence.
How the Mortgage Credit Certificate Works
TSAHC issues MCCs to buyers who meet specific income and purchase price limits in Collin County. You can combine an MCC with down payment assistance, which maximizes your total financial benefit. The catch is timing – you must apply through your lender before closing. It can’t be issued after the fact, so bring it up early in your conversations with your loan officer.
Finding a Local Lender
Not every lender can originate TSAHC and TDHCA loans. Only approved lenders are trained on the compliance rules and income limits specific to Collin County. It’s worth interviewing a few of them to compare interest rates and fee structures. The right loan officer will handle all the paperwork required to secure your grant or forgivable lien – that’s a meaningful part of what you’re choosing when you pick a lender.
How to Apply for Assistance in Collin County
Start by pulling your financial documents together: recent pay stubs, two years of W-2s, two years of tax returns, and current bank statements. Once that’s organized, you submit to an approved lender for pre-approval. They’ll pull your credit report and verify you meet the 620 minimum score required by the TDHCA.
It’s not a complicated process, but it does require some upfront organization on your end.
Estimating Your Budget
Here’s a concrete illustration: if you buy a $400,000 home with an FHA loan and a 3.5% down payment, your base loan amount is $386,000. At a hypothetical 6% interest rate, your principal and interest payment comes out to roughly $2,314 per month. Add Collin County property taxes, homeowners insurance, and mortgage insurance on top of that. Your lender will calculate the full monthly obligation against your gross income to land on your actual maximum purchase price.
Taking the Next Step
Once you have your pre-approval letter, you’ll know exactly how much house you can afford and how much assistance you qualify for. Sellers take that letter seriously – it tells them your financing isn’t a question mark. With Plano homes going under contract in roughly 37 days, having it in hand before you start shopping lets you move when the right house comes up rather than scrambling to catch up.
Frequently Asked Questions
Does Texas have a first-time home buyer program and how do you qualify?
Yes, Texas offers programs through the TDHCA and TSAHC. You qualify by meeting income limits – $181,650 for standard areas in Collin County – maintaining a minimum credit score of 620, and working with an approved lender to process your application.
What disqualifies you as a first-time home buyer?
Owning a primary residence in the past three years disqualifies you. So does earning more than the Collin County income limit of $181,650, or carrying a credit score below 620. All three are firm cutoffs for these specific state programs.
What is the first-time home buyer grant in Plano and how much is it?
Buyers in Plano can access the TDHCA My First Texas Home program, which provides up to 5% of the loan amount. That money is structured as either a straight grant or a 0% interest, no-monthly-payment second lien forgiven after three years.
How much down payment do first-time buyers need in Texas?
It depends on your loan type. FHA loans require at least 3.5% down. VA loans allow eligible buyers to purchase with zero down. State assistance programs can often cover these minimum requirements entirely.
What salary do you need to afford a $300K–$400K house in Plano, TX?
The honest answer is that it depends on current interest rates, property taxes, and your existing debt load. Using the 3-3-3 rule as a guide, you’d want your total monthly housing payment to stay under 33% of your gross income.
How long does the application and approval process take for Plano first-time buyers?
Typically a few weeks once you submit your documents to an approved lender. Since homes in Plano are spending a median of 37 days on the market, you’re better off securing your pre-approval before you start looking at houses – not after.
How do first-time home buyer tax credits work when buying in Plano?
Texas offers Mortgage Credit Certificates (MCC) that let you claim a portion of your mortgage interest as a dollar-for-dollar tax credit. You must apply through your lender before closing on your Collin County home – it can’t be added after the fact.
What are the main assistance options for purchasers in Collin County?
Most of the meaningful assistance comes through state-level agencies like the TSAHC and TDHCA. These homebuyer programs in Plano pair competitive interest rates with funds to help cover your down payment and closing costs.
Does state assistance restrict the property I can purchase?
The primary requirement for these funds is that the property must serve as your primary residence. While you cannot use the money for an investment property, you can apply the assistance toward various types of homes in Plano as long as you live there.